Track regulatory change with dates, sources and context attached.
Follow source-backed telecom tax and regulatory developments with clear jurisdiction, status, publication/effective dates and expert-reviewed context. Not legal advice.
Expert review is a publication requirement, not a claim that reviewed updates are available here.
Regulatory Change content summarizes and contextualizes source material. It is not legal advice and must not be treated as a substitute for the authoritative regulation, order, notice, statute or professional advice applicable to a reader's circumstances.
No approved regulatory items, sources, jurisdictions or reviewer assignments were supplied. The library below is intentionally empty; the labeled patterns explain how approved content would be read.
Evidence before an update.
A current item belongs here only when its source, scope, dates, status and context have been approved.
No approved regulatory updates available.
This page does not report current changes or imply coverage of any jurisdiction. Until approved items are supplied, explore the supporting resources without treating them as regulatory authority.
Find the scope. Keep the source.
Default library: approved data absent. Discovery controls below are an illustrative design pattern, not a working search or a claim of available results.
Effective-date filtering is available only when the approved source establishes it. Other sort patterns: Upcoming effective and Recently updated. No countries, services, authorities or result counts are inferred.
No source-approved matches to display.
Preserve the selected filters; offer reset rather than fabricated related changes. This specimen has no submitted query or selected record.
An update is more than a headline.
The source, jurisdiction and lifecycle state travel with every summary. Publication is not an effective date; a proposal is never labeled a new law.
A detail link leads to the source-backed reading page, not a sales form. Record identity uses stable content, source and jurisdiction ID fields; no records or identifiers have been invented here.
Source-approved change title
Exact jurisdiction — source required. A concise, scoped summary belongs here only after the material facts and context have been approved.
A source-led reading experience.
Illustrative detail anatomy only. No legal article, regulatory conclusion or source document has been supplied.
The intended reading order keeps the summary, dates, ordered timeline and approved direct sources in the page. Search and filters are not prerequisites for reading.
Static design pattern: these reading links and source slots are not live controls. No authority URLs have been invented.
Source-approved change title
Exact jurisdiction — source required. Issuing authority — primary source required. Any direct summary must keep its source, scope, date and status qualification attached.
Status — not establishedWhat changed
State only what the approved source establishes. Attach an exact citation to each material date, obligation, rate, scope, filing requirement, exemption or authority action. No change can be summarized here before that evidence exists.
Primary document comes first.
Source unavailable: publication remains pending. This is a descriptive link pattern, not a reference to an actual document.
Read events with their evidence attached.
List order is symbolic, not a claim about event sequence. An approved article orders events by the chronology its sources establish.
Who or what may be affected
Identify the exact jurisdiction, entities and telecom services named in the approved source. Preserve exceptions and limits. An editorial relevance tag does not establish that a reader or customer is affected.
Context, not a new legal conclusion
Explain how approved source facts connect to telecom tax research. Attribute analysis and distinguish it from the source's words. A legal conclusion is included only when the exact approved source and required review support it; do not infer one.
What remains unclear?
Record what the approved source does not resolve. A pending clarification stays pending; uncertainty must not become an invented deadline, scope or obligation.
What may need investigation?
A source-backed change may affect a scoped workflow. This is a question for investigation, not an instruction that a company must act or a claim of non-compliance.
Is the exact jurisdiction and issuing authority verified?
Is the source proposed, final, effective or historical?
Which date does the authoritative source actually establish?
Which entities and telecom services are explicitly in scope?
What remains unclear in the approved source?
Any product relevance must be conditional and separately substantiated. Check Coverage independently; editorial attention to a jurisdiction does not mean ZoikoTax supports it.
Coverage · /coverage/ →Secondary context follows the primary source and is labeled as explanatory, never a replacement for authority.
Recency is not legal effect.
Lifecycle vocabulary below is explanatory. No status has been assigned to a regulatory item on this page.
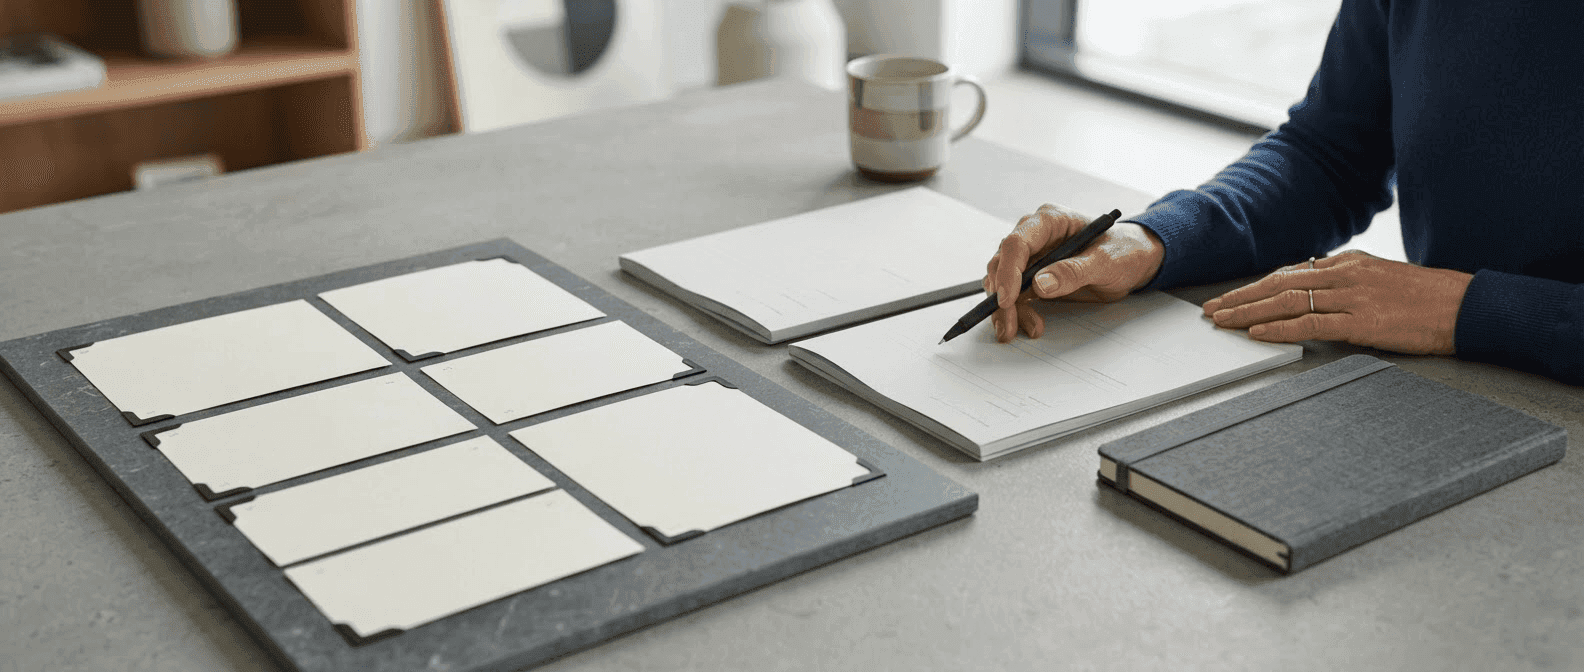
Every date has a different job.
Unknown, pending and absent remain explicit. No dates, deadlines or review cadence are supplied; publication is never substituted for effect.
Readable ordered-list pattern, not a horizontal-only chart. The letters indicate structure, not actual legal chronology or dates.
Relevance is a research question.
These eight editorial categories help organize investigation. They are not findings of customer applicability, obligations or production support.
Tax determination
May affect source-backed treatment or calculation inputs within the exact approved scope.
Sourcing / jurisdiction
May affect how a transaction's location or jurisdiction is assessed; exact source scope matters.
Exemptions / certificates
May affect an exemption or evidence requirement only where the approved source establishes it.
Regulatory obligations
May affect an authority-defined requirement; proposal, final and effective states remain separate.
Compliance & filing
May affect a scoped reporting or filing workflow. No deadlines or duties are inferred.
E-Invoicing & CTC
May affect source-established invoicing or CTC requirements; production support is a separate question.
Remittance
May affect a source-defined payment or remittance process. This does not imply ZoikoTax holds funds.
Billing / product
May affect scoped billing treatment or product interpretation; service taxonomy must be approved.
A topic or jurisdiction appearing in an article never establishes activated ZoikoTax capability. Product relevance needs separate evidence; Coverage is the route for capability questions.
A clear record, even when the answer changes.
Keep the publication, editorial updates, source checks, effective date, source scope and reviewer distinct. An unchanged source is not an automatic guarantee of currentness.
This record is historical.
It is not the current update. A successor may be linked only when known and source-approved; otherwise show “Successor — source required.”
Currentness not confirmed.
A stale review fails closed: withhold current presentation until the source and scope are checked and the required review is approved. No review cadence was supplied.
Keep historical records distinct.
Withdrawn, repealed, replaced and superseded records are removed from default current discovery. Retain their historical context without a current-action prompt.
Corrections leave a trail.
A governed correction log records what changed, why, the supporting source and approval. Published and Last updated stay separate. No correction events are claimed here.
A removed source is not replaced by guesswork.
Retain any approved citation, flag access loss and seek an official replacement. A missing source is a review trigger, not permission to invent authority.
Review is a requirement. Not an invented credential.
These are required ownership roles, not assigned people. Public names, roles and profile links appear only after approval; no reviewer identity, biography or review date has been supplied.
Source, dates, exact jurisdiction, lifecycle status, expert review, legal boundary, accessible reading and approved routes must pass the publication gates. This design does not claim that those gates, production accessibility or release checks have passed.
Direct answers. No inferred obligations.
Source-required answers for this approval candidate. No current regulatory update or legal advice is being presented.
What changed in telecom tax regulation?
No approved regulatory item was supplied, so this page does not assert a change. A published answer must identify the exact jurisdiction, authority, status, dates and supporting source.
When does this regulatory change take effect?
Only an approved authoritative source can establish the effective date. No such source is supplied here: Effective date — not established. A publication or update date is not a substitute.
Which authority issued the change?
The exact issuer must be verified against the primary source. No issuing authority is identified here because no approved source or jurisdiction record was supplied.
Is this proposal final or effective?
Status must be separately established from the approved source. Proposed, adopted / final and effective are different states; neither finality nor effect is inferred from recency. No item status is established here.
What source supports this update?
An approved authoritative source with an exact citation is required. None was supplied. Secondary commentary or news discovery alone cannot stand in for authority; the summary stays source-required.
Does this mean ZoikoTax supports the jurisdiction?
No. Editorial relevance does not establish production coverage. Check Coverage separately for capability information; no jurisdiction support is inferred from this page.
Context first. Capability questions separately.
Explore capability information independently. An editorial topic does not establish supported jurisdictions or activated functionality.
Learn about the platform separately. Any connection between a regulatory item and a product capability needs its own approved relevance evidence.
Keep research grounded in evidence.
Use Resources for editorial context and Coverage for capability questions. Neither replaces the authoritative source or advice for your circumstances.